NEWS & INSIGHTS
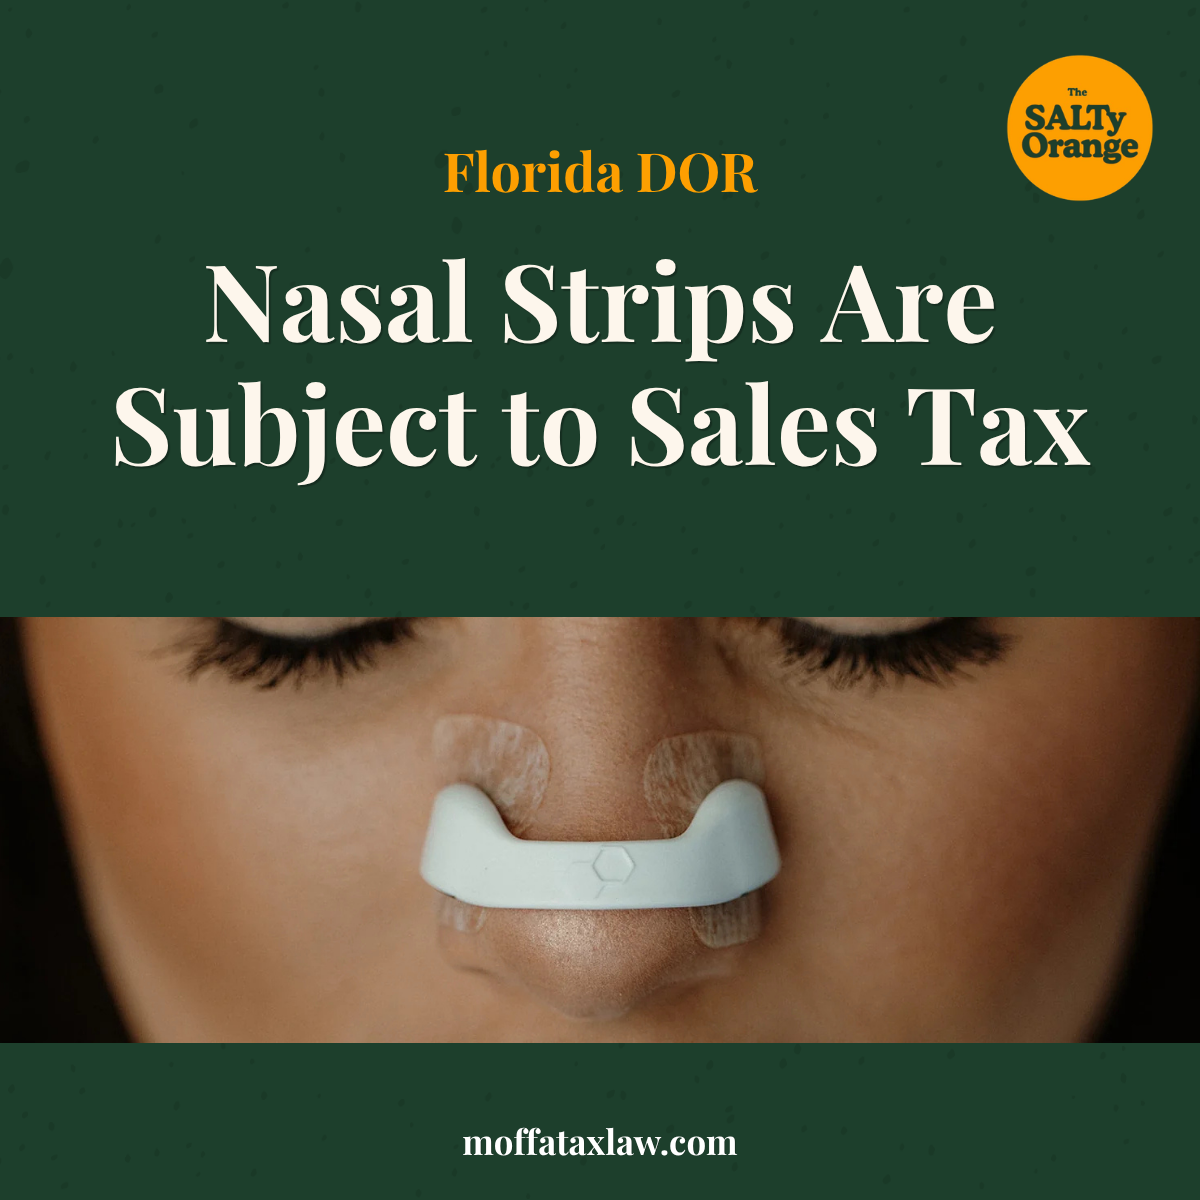
The Florida Department of Revenue has determined that sales of certain adhesive nasal strips are subject to Florida sales and use tax, despite their use as a breathing support device.
In Technical Assistance Advisement 26A-011, the Department concluded that the nasal strips are taxable and subject to any applicable discretionary sales surtax based on where the product is delivered.
Nasal Strips Marketed for Post Surgical Breathing Support
The taxpayer develops and sells adhesive nasal strips that are applied externally across the nose to improve airflow by lifting and stabilizing the nasal passages.
According to the TAA, the drug free product is primarily used following rhinoplasty procedures, when patients may experience nasal obstruction caused by swelling, inflammation, or temporary structural instability. The product does not carry an RX label and contains no medical or inactive ingredients.
The taxpayer argued that the product functions as a medical device because it helps alleviate impaired breathing and supports recovery following surgical procedures. Its noninvasive and drug free characteristics, the taxpayer maintained, did not change its primary medical purpose.
Medical Use Alone Does Not Create a Sales Tax Exemption
Florida generally imposes sales tax on tangible personal property unless a specific exemption applies. Medical products, supplies, and devices are not automatically exempt simply because they serve a medical purpose.
Under the provisions discussed in the TAA, medical items may qualify for an exemption when they are dispensed under an individual prescription, included on Florida’s Nontaxable Medical Items and General Grocery List, or used to treat a patient and temporarily or permanently incorporated into the patient by a licensed practitioner.
The Department found that the nasal strips did not meet any of those exemptions. As a result, Florida sales of the product are taxable.
Delivery Location Determines Applicable Surtax
In addition to Florida sales and use tax, sales of the nasal strips are subject to any applicable discretionary sales surtax based on where the product is delivered.
The TAA applies only to the specific taxpayer and facts presented. The Department cautioned that changes in statutes, administrative rules, or judicial interpretations could result in different tax treatment for similar transactions in the future.
Florida State and Local Tax Litigation
Explore our Florida State and Local Tax Litigation. Businesses facing Florida tax disputes should be prepared for the possibility that litigation may continue beyond the trial level. Understanding how tax cases move through Florida’s appellate courts can be critical to protecting favorable rulings and challenging adverse decisions.
© 2025 Jeanette Moffa. All rights reserved.
The nasal strips addressed in TAA 26A-011 are subject to Florida sales and use tax.
No. Medical products, supplies, and devices must qualify for a specific exemption to be sold tax free.
The Department found that the strips did not meet any of the specific medical product exemptions discussed in the TAA.
No. Medical use alone does not establish an exemption from Florida sales tax.
Certain medical products and supplies may qualify for an exemption when dispensed according to an individual prescription from an authorized prescriber.
Yes. The Department references the Nontaxable Medical Items and General Grocery List, Form DR-46NT.
When applicable, yes. The surtax is determined based on where the product is delivered.
It is a Florida Department of Revenue Technical Assistance Advisement addressing the sales and use tax treatment of the nasal strips described by the taxpayer.
No. The TAA is binding on the Department only under the specific facts and circumstances presented in the request.
Additional Articles by the SALTy Orange at Moffa Tax Law:
Florida DOR Says Nasal Strips Are Subject to Sales Tax
NEWS & INSIGHTS Florida DOR Says Nasal Strips Are Subject to Sales Tax Florida has determined that certain drug free…
The Line Between Voter Information and Political Advocacy in Florida Ballot Language
NEWS & INSIGHTS The Line Between Voter Information and Political Advocacy in Florida Ballot Language Florida’s proposed property tax amendment…
Highlands County Shifts Tourist Tax Collection from DOR
NEWS & INSIGHTS Highlands County Shifts Tourist Tax Collection from DOR The Florida Department of Revenue has announced that Highlands…
Jeanette Moffa, Esq.
(954) 800-4138
JeanetteMoffa@MoffaTaxLaw.com
Jeanette Moffa is a Partner in the Fort Lauderdale office of Moffa, Sutton, & Donnini. She focuses her practice in Florida state and local tax. Jeanette provides SALT planning and consulting as part of her practice, addressing issues such as nexus and taxability, including exemptions, inclusions, and exclusions of transactions from the tax base. In addition, she handles tax controversy, working with state and local agencies in resolution of assessment and refund cases. She also litigates state and local tax and administrative law issues.